What Happens to My TPD Claim If I’ve Already Received Compensation?
Overview
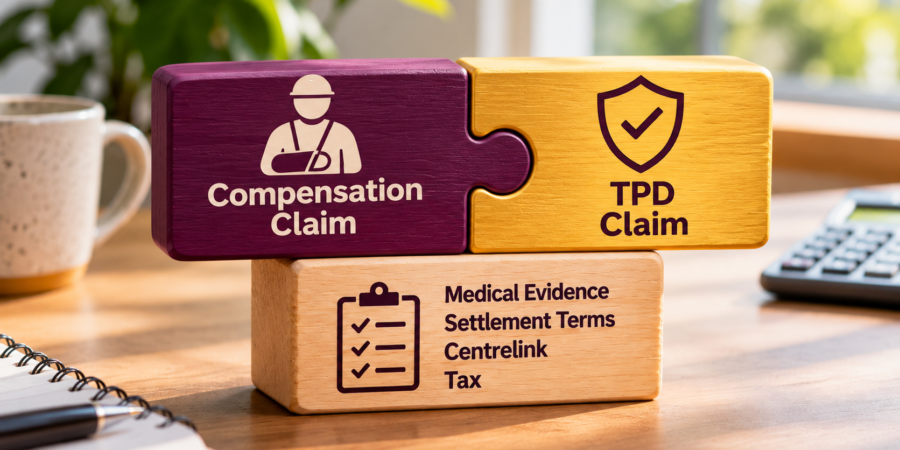
A lot of people who settle a workers compensation or personal injury claim assume their TPD claim went with it. Often it hasn’t. In many cases, a TPD claim after compensation is still possible, because the two claims come from separate systems. But they can still cross over in important ways, particularly around medical evidence, settlement terms, Centrelink and tax.
Below, we walk through where the two claims cross over. We also cover the questions worth asking before you settle, lodge a claim or move any money.
Why a compensation payout and a TPD claim are separate
A compensation claim is usually made against an employer, a workers compensation insurer, a CTP insurer or another party responsible for an injury. A Total and Permanent Disability (TPD) claim is different. It is made under an insurance policy, often held through your superannuation fund, and it depends on whether you meet that policy’s definition of TPD.
Take a common example. Someone settles a workers compensation claim with their employer’s insurer, then later receives a TPD benefit from their super fund’s insurer. Each claim is generally assessed under its own rules, although the evidence, policy wording and settlement terms can still interact.
Many Australians hold TPD cover through their super without realising it. If you have more than one super fund, you may have cover in more than one place.
Where the two claims can overlap
Medical evidence from your compensation claim
Your compensation claim probably produced a stack of paperwork: medical reports, capacity assessments, rehabilitation records. A TPD insurer can ask for all of it. A report saying you can do some type of work does not automatically sink a TPD claim. But if one report says one thing and another says something different, expect questions from the insurer.
The wording of your settlement deed
Most compensation settlements end with a deed of release, which usually deals with the parties to that compensation claim. Some deeds are worded broadly, though, with clauses covering “all claims” or future claims. That is worth checking carefully, especially if the same insurer is involved in more than one of your claims.
If you haven’t signed yet, ask your compensation lawyer whether anything in the deed could affect a TPD or income protection claim. If you already have, keep a copy for your TPD claim file.
Whether your cover was still in place
Once you stop working, contributions into your super usually stop too. Under current super rules, insurance on an inactive super account can be cancelled after 16 months without contributions or rollovers, unless you have elected to keep the cover. Fund-specific rules can also affect when cover ends.
Many people only find out their cover has ended when they try to claim. That isn’t always the end of the road. A TPD claim usually turns on whether cover was in force at the policy’s relevant disablement date, which may be linked to when you stopped work because of the injury or illness. The relevant date varies by policy.
Income protection, which is more likely to be reduced
Income protection pays a monthly benefit rather than a lump sum, and many policies reduce those payments by workers compensation or other income received for the same period. So if you hold both types of cover, income protection is more likely than TPD to be cut back by compensation payments.
The two claims can still run side by side. Some people receive income protection payments while their TPD claim is being assessed, so it’s worth checking whether your fund holds both for you.
Any offset clause in your TPD policy
Offset clauses are less common in lump sum TPD cover, but some policies have them. These clauses let the insurer reduce a benefit by other amounts received for the same injury or illness. Whether one applies to you comes down to the exact policy wording.
“A compensation settlement and a TPD benefit can both form part of the money you live on for years. They work best when they are planned together, not one after the other.”
How Centrelink treats a TPD payment after compensation
A lump sum TPD benefit paid from a superannuation fund is not generally treated as compensation for Centrelink compensation recovery purposes. It does not usually create its own preclusion period. However, it does not reduce or cancel a preclusion period already created by a compensation payment.
The part people often miss is what happens next. Once the money is withdrawn from super, what you do with it can affect the income and assets tests, and in turn payments such as the Disability Support Pension. Payments from disability or personal insurance held outside super can be treated differently, depending on what the payment is for and how the policy is structured.
Tax differences between compensation and TPD
Compensation and TPD payments can be taxed very differently. Some personal injury compensation amounts may be capital rather than ordinary income, but that depends on what the payment represents and how it is structured. Interest or investment earnings on the funds may be taxable either way.
A TPD benefit paid from super may have both tax-free and taxable components. Special rules can increase the tax-free component for a qualifying disability superannuation benefit. Two people with similar payouts can end up with quite different after-tax amounts, so it pays to have this worked out on your own figures.
Can I still make a TPD claim after compensation?
In many cases, yes. The main questions are whether the relevant cover was still in force, whether you meet the policy definition, and whether the evidence supports the claim. Some people lodge their TPD claim while the compensation claim is still running. Others lodge it after settlement.
Leaving it too long can cause problems. Medical evidence gets harder to pull together as time passes, and some policies and complaint processes have time limits. If your TPD claim was declined in the past, you may be able to ask for an internal review or take a complaint to the Australian Financial Complaints Authority (AFCA).
Planning for both payouts together
Two lump sums often land months apart, and what you do with the first can narrow your options for the second. For example, paying off debt or investing a compensation payout without allowing for a pending TPD benefit can affect your cashflow, your Centrelink position and the tax on earnings or later transactions.
Before moving either payout, it helps to know what is coming in, when it is coming, how long any preclusion period lasts, and what Centrelink or super consequences may follow. HFI works with compensation lawyers and clients to model this before key decisions are locked in. Our guide to post-TPD financial advice covers what to think about once a TPD claim is approved.
Received compensation and unsure about your TPD claim? Let’s talk before you make decisions about your payout.
A short conversation can help you understand how your claims interact and what to plan for next.
Call 1300 10 44 99 Read: Preclusion Period GuideRelated reading
- How compensation affects payments, Services Australia
- Social Security Guide 4.13 Compensation, Department of Social Services
- Protecting Your Super package: frequently asked questions, APRA
- Insurance through super, Moneysmart
- HFI: Centrelink Preclusion Period Explained
- HFI: Post‑TPD Financial Advice (After Approval)
- HFI: Financial Advice After a Compensation Settlement
- HFI: DSP Asset Limits: How Much Can I Have in the Bank?
Important information
This article is general information only and does not take into account your personal circumstances. TPD claims and compensation settlements can have Centrelink, tax, legal and insurance consequences that vary significantly depending on your situation and the wording of your policy and settlement documents. You should seek advice from qualified financial, legal and tax professionals before making any decisions. Centrelink rules, superannuation rules and thresholds change over time. Verify current information with Services Australia, your super fund or your insurer before acting. HFI does not provide legal advice or tax agent services unless expressly stated. You should check settlement wording with your lawyer and tax consequences with a registered tax professional.
Health & Finance Integrated is a Corporate Authorised Representative of Able Financial Services, ABN 27 646 319 164, AFSL 530596, Shop 6, 23 Hassall St, Parramatta 2150 NSW.